How to Get a Home Loan with a Low CIBIL Score (2026 Guide)
Low CIBIL score? What lenders look at, how to fix errors in your credit report, and practical steps that improve your chances of a home loan in Delhi.
 Neev Residency teamUpdated 7 min read
On this page
You've found the right flat, and then the bank says your CIBIL score is too low. It happens to a lot of buyers, often because of one missed credit card bill or a mistake in the report. Here's what the score means, what lenders look at, and the steps that help.
What is a CIBIL score?
A CIBIL score is a three-digit number, from 300 to 900, calculated by TransUnion CIBIL from your credit history: loans, credit cards, how you've repaid them and how much credit you use. Banks and housing finance companies check it when you apply for a home loan.
The closer your score is to 900, the more confidence a lender has in you, and the better your chances of approval. There is no single score that guarantees a loan: each lender sets its own cut-off and looks at your income, job and the property as well.
CIBIL is one of four credit bureaus licensed in India. Your score can differ slightly from one bureau to another because each one uses its own model.
Why is your score low?
CIBIL's own guide lists the factors that move your score. Most low scores come down to one of these:
- Payment history. Late or missed EMIs and credit card dues pull your score down most, and they stay on your record.
- Credit utilisation. Using most of your credit card limit every month suggests you depend on credit.
- Credit mix and age. A short history, or only unsecured loans such as personal loans and cards, gives lenders less to go on.
- Enquiries. Every time you apply for a loan or card, the lender checks your report. Many applications in a short time look like credit hunger.
- Errors. A loan you closed shown as open, a payment marked late that you made on time, or someone else's account on your report.
How do you check your report for free?
The Reserve Bank of India requires every credit bureau to give you one free full credit report, including your score, once each calendar year. You can request yours on CIBIL's website with your PAN and mobile number.
Don't stop at the score. Read the report line by line:
- Personal details: name spelling, date of birth, PAN and addresses.
- Accounts: every loan and card should be yours, with the right status (active or closed).
- Payment history: look for "days past due" entries you don't recognise.
- Enquiries: check that every lender listed is one you actually applied to.
Checking your own report does not count as a loan enquiry and does not lower your score.
How do you fix an error in your credit report?
Raise a dispute with the credit bureau online, with proof such as a loan closure letter or a bank statement showing the payment. The bureau checks with the lender that reported the data.
Under RBI rules, the lender and the bureau have 30 days to resolve your complaint. If they take longer, you are owed ₹100 for each day of delay, which the RBI says must be credited to your bank account within five working days of the complaint being resolved.
What helps you get a home loan with a low score?
If you need the loan soon and your score won't recover in time, these steps make your application stronger:
1. Add a co-applicant with a strong record
A spouse or parent with a good score and a steady income can apply with you. The lender looks at both of you, and the combined income can also raise the loan amount you qualify for. Remember that the co-applicant is equally responsible for the EMIs.
2. Make a bigger down payment
The smaller the loan compared with the flat's value, the less risk the lender takes. RBI already caps home loans at 90% of the property's value for smaller loans, 80% for mid-sized loans and 75% for loans above ₹75 lakh. Offering to pay more than the minimum yourself shows commitment.
3. Ask for a smaller loan
A smaller loan means a smaller EMI, which is easier to fit within your income. Try different amounts in our EMI calculator to see what's comfortable before you apply.
4. Show stable income
Recent salary slips, Form 16, income tax returns and bank statements that show regular credits all help. If you've been in the same job for years, say so.
5. Clear small dues first
An overdue credit card bill or a small loan in default does more harm than its size suggests. Pay it off, get it marked as closed, and keep the proof.
6. Apply to one or two lenders, not ten
Each application adds an enquiry to your report. Ask lenders about their criteria first, then apply where you fit.
7. Consider a housing finance company
Banks aren't the only option. Housing finance companies and NBFCs set their own criteria and may consider applicants a bank turned down. The interest rate can be higher, so compare the full cost, including processing fees, before you sign.
8. Choose a flat the bank can lend on
A loan depends on the property too. Banks ask for the title deed, the chain of earlier deeds and an encumbrance certificate. A registry flat with a clean chain of papers is easier to finance than a flat held only on GPA. Our guide to GPA vs registry in Delhi explains the difference.
How long does it take to improve your score?
There's no fixed timeline. Your score updates as lenders report new data to the bureau, which they do regularly. A corrected error can show up within weeks. Rebuilding after missed payments takes longer: what matters is a steady run of on-time payments and lower credit card use.
A good routine while you wait:
- Pay every EMI and credit card bill in full and on time. Set up auto-debit.
- Keep your credit card use well below the limit.
- Don't close your oldest credit card. Its long history helps you.
- Don't apply for new credit cards or personal loans in the months before your home loan application.
What does the bank need besides a good score?
Your score opens the door, but the lender also checks:
- Income and job stability: salary slips, ITRs and bank statements.
- Existing EMIs: the total of all your EMIs, including the new one, compared with your income.
- Age: the loan tenure usually has to end before you retire.
- The property: clear title, approved papers and a fair value as per the bank's valuer.
- Your own contribution: the down payment, plus stamp duty and registration charges, which most loans don't cover. Work out the stamp duty with our stamp duty calculator.
Looking for a flat you can finance?
Neev Residency lists registry flats in Uttam Nagar, Dwarka Mor and Nawada, close to the Blue Line metro. Tell us your budget and loan situation, and we'll show you flats whose papers a bank can work with.
Frequently asked questions
What is a CIBIL score?
A three-digit number from 300 to 900 that sums up your credit history. The closer it is to 900, the more confidence a lender has in lending to you.
Can I get a home loan with a low CIBIL score?
Sometimes, yes. Each lender sets its own cut-off. A bigger down payment, a smaller loan or a co-applicant with a strong record can help, but expect stricter terms.
How do I check my CIBIL score for free?
Under RBI rules, every credit bureau must give you one free full credit report, including your score, once each calendar year. You can request it from CIBIL's website.
How long does a credit bureau take to fix an error?
RBI rules give lenders and credit bureaus 30 days to resolve a complaint. After that, you are owed compensation of ₹100 for each day of delay.
Does checking my own score lower it?
No. Checking your own report is not a loan enquiry. What counts are enquiries made by lenders when you apply for credit, so avoid applying to many lenders at once.
How much of the flat's price will a bank lend?
RBI caps the loan at 90% of the property's value for smaller loans, 80% for mid-sized loans and 75% for loans above ₹75 lakh. You pay the rest as a down payment.
General information, not legal advice. Confirm with a lawyer or your sub-registrar.
Sources
- TransUnion CIBIL: Free CIBIL score and report
- TransUnion CIBIL: Understanding your credit report (PDF)
- Reserve Bank of India: Free full credit report once a year from each credit bureau
- Reserve Bank of India: Compensation for delayed updation or rectification of credit information
- Reserve Bank of India: Housing loans, loan-to-value ratios (circular, 2015)
Area guides
Flats mentioned in this guide
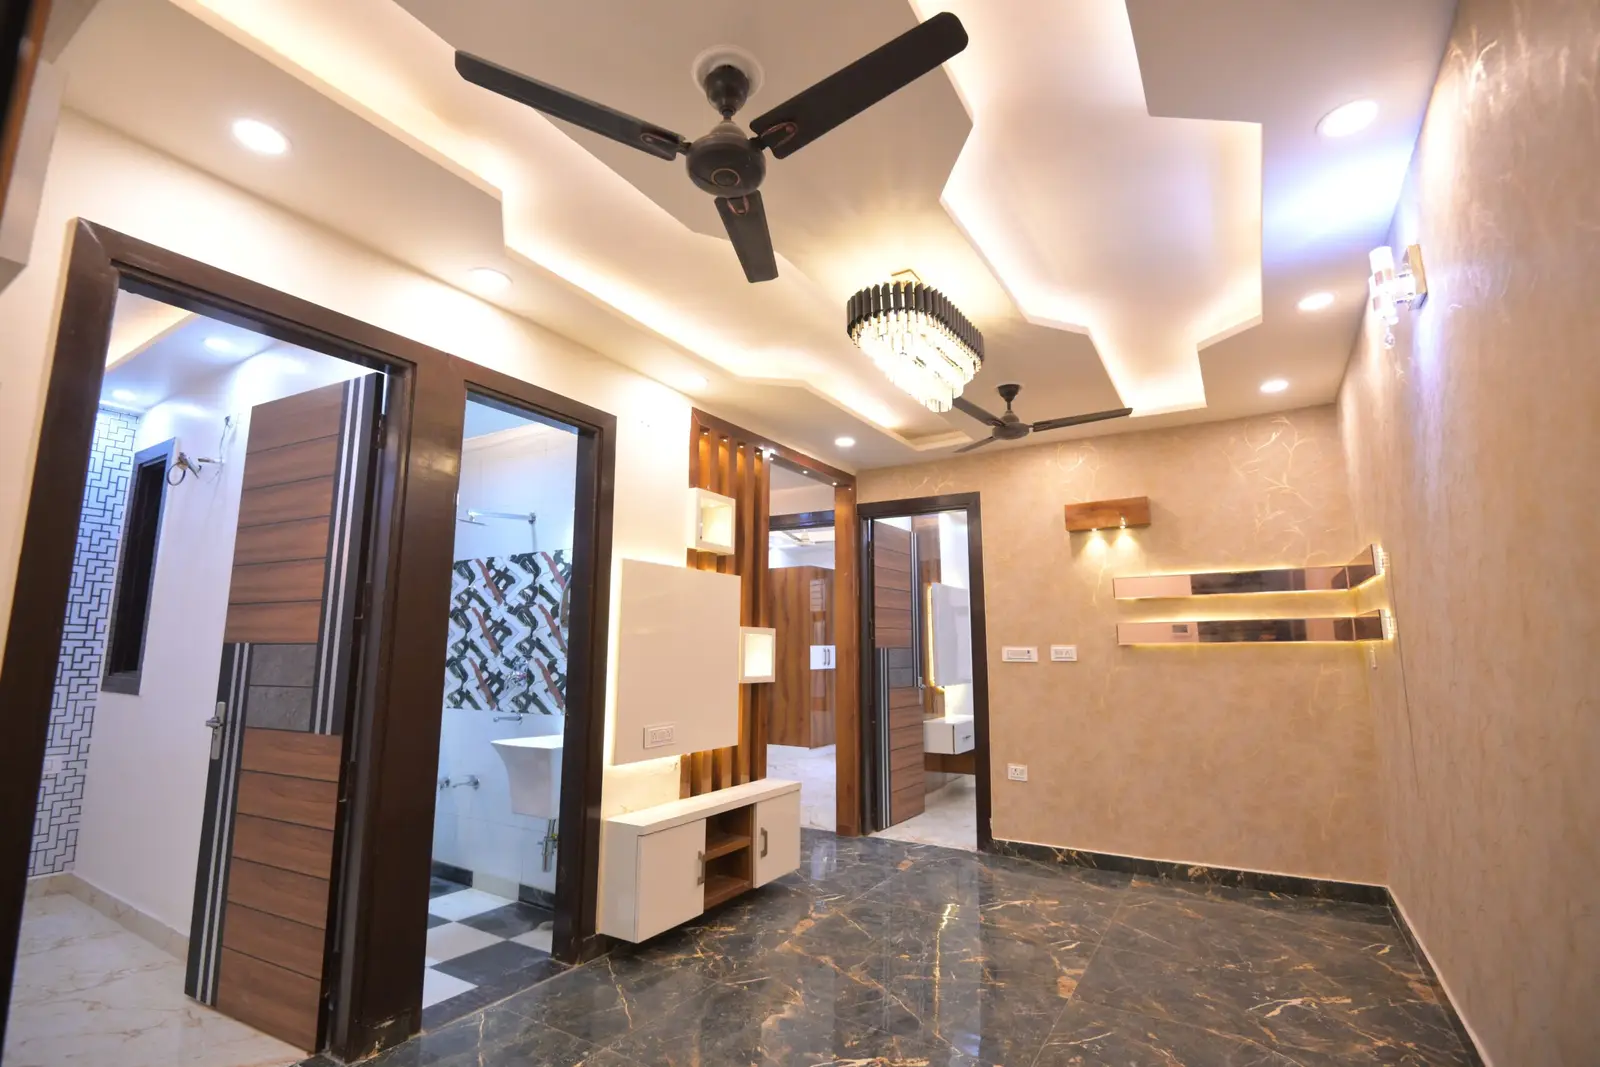 5 photos#202605
Price on call
Call for price2 BHK Registry Flat, Dwarka Mor
2 BHK Flat · Dwarka Mor
495 sq ft
- Registry
- Lift
- Parking
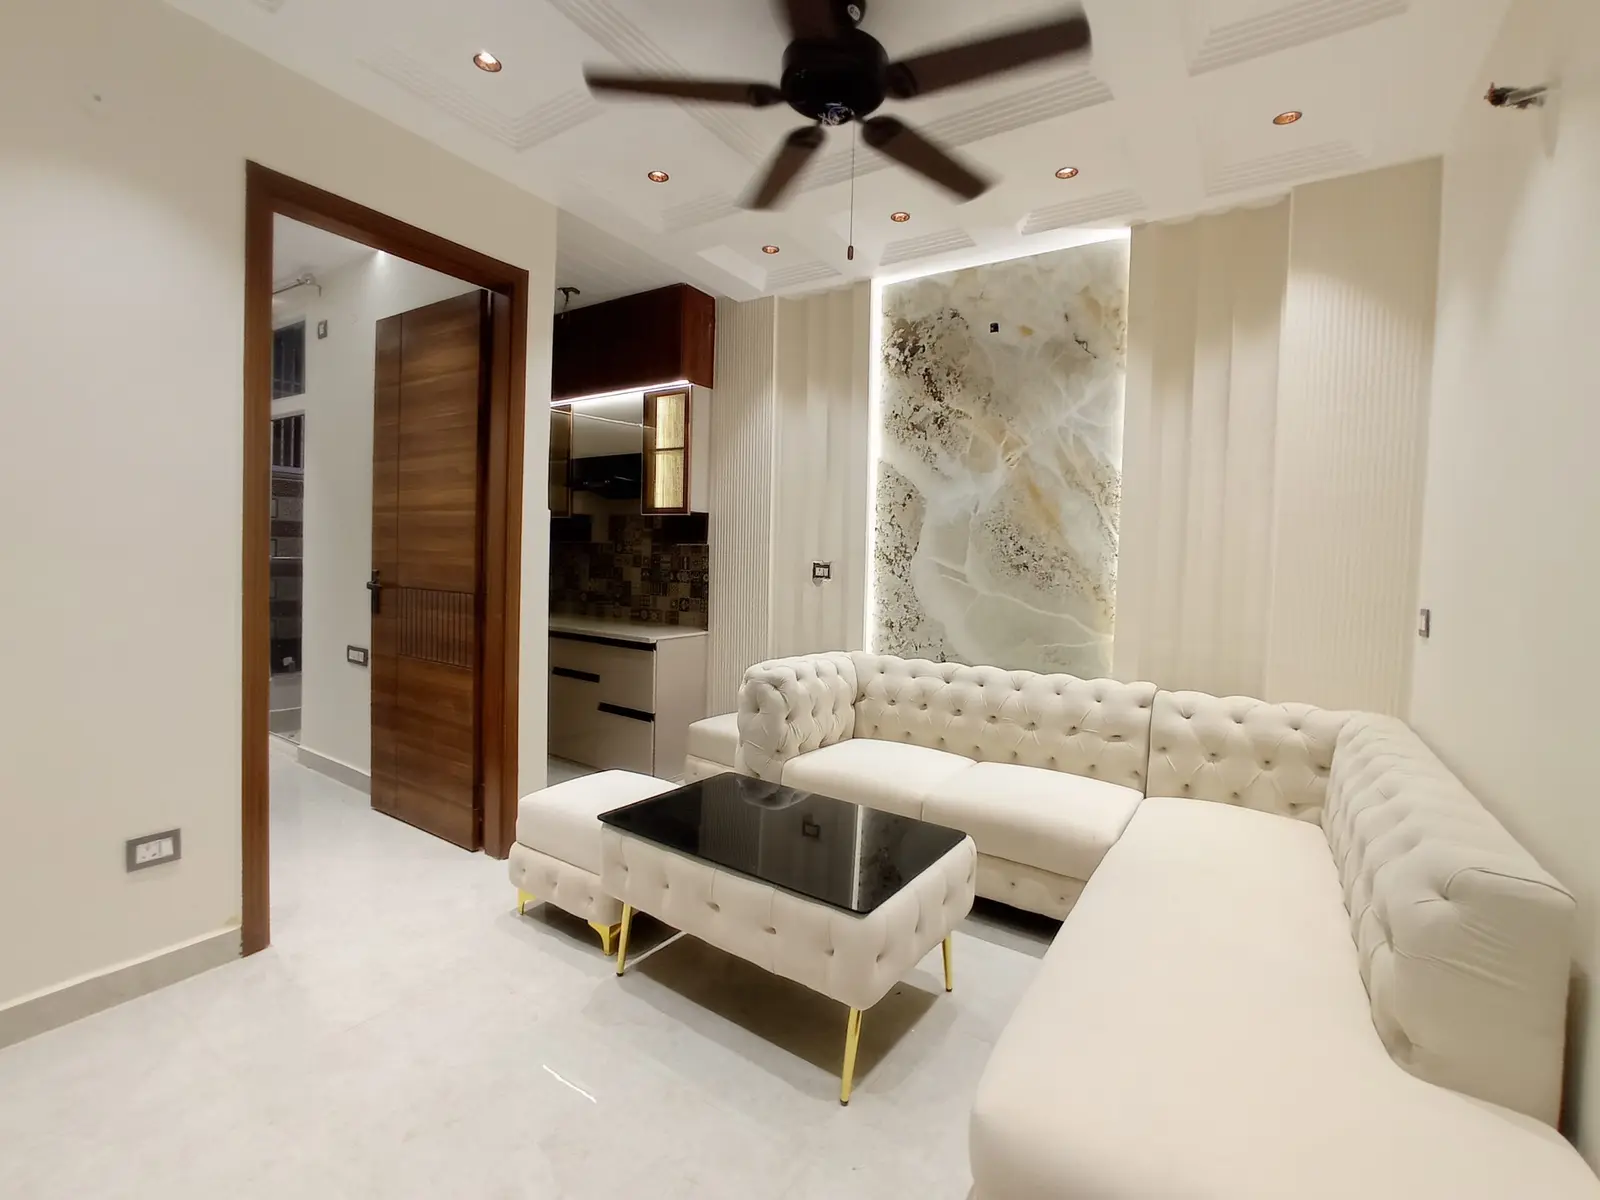 4 photos#202610
Price on call
Call for price1 BHK Flat Near Metro, Nawada
1 BHK Flat · Nawada
360 sq ft
- Near Metro
- Lift
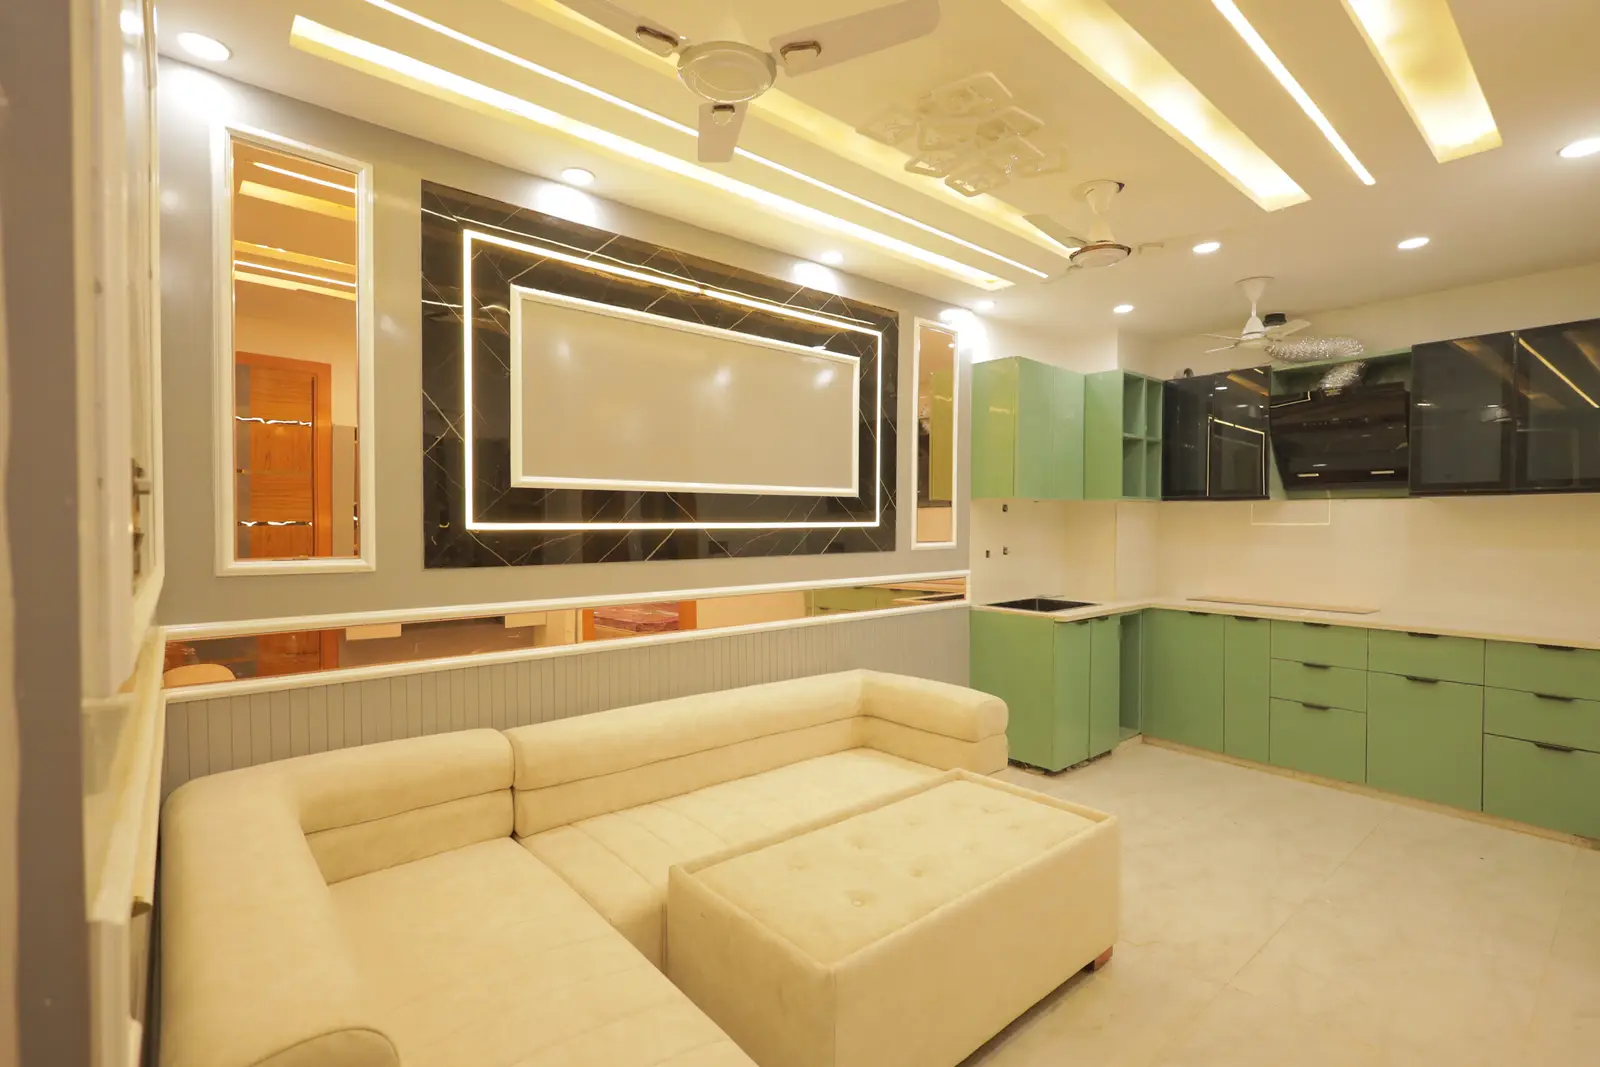 5 photos#202604
Price on call
Call for price2 BHK Furnished Flat, Dwarka Mor
2 BHK Flat · Dwarka Mor
540 sq ft · Semi or fully furnished
- Lift
- Parking